Rules as of 29 October 2026
Work out net pay, PAYE, SHIF, housing levy and NSSF for any month since January 2023. See what your employer pays on top, work back from a net figure, and compare two months line by line.
Private by design. Everything is calculated in your browser. Nothing you type is sent to us, saved or added to the address bar. Your figures leave this page only if you tap “Copy link” or “Share on WhatsApp”.
Net pay
Estimate for a resident employee, for guidance only. Not tax advice.
For employers
This calculator runs on the same engine as Beep HR & Payroll. Add your team once, and payroll, payslips and statutory returns follow.
The same Kenyan rules for every employee, every month: PAYE, SHIF, housing levy and NSSF, calm payslips, P9 and P10 for iTax, leave, attendance and appraisals.
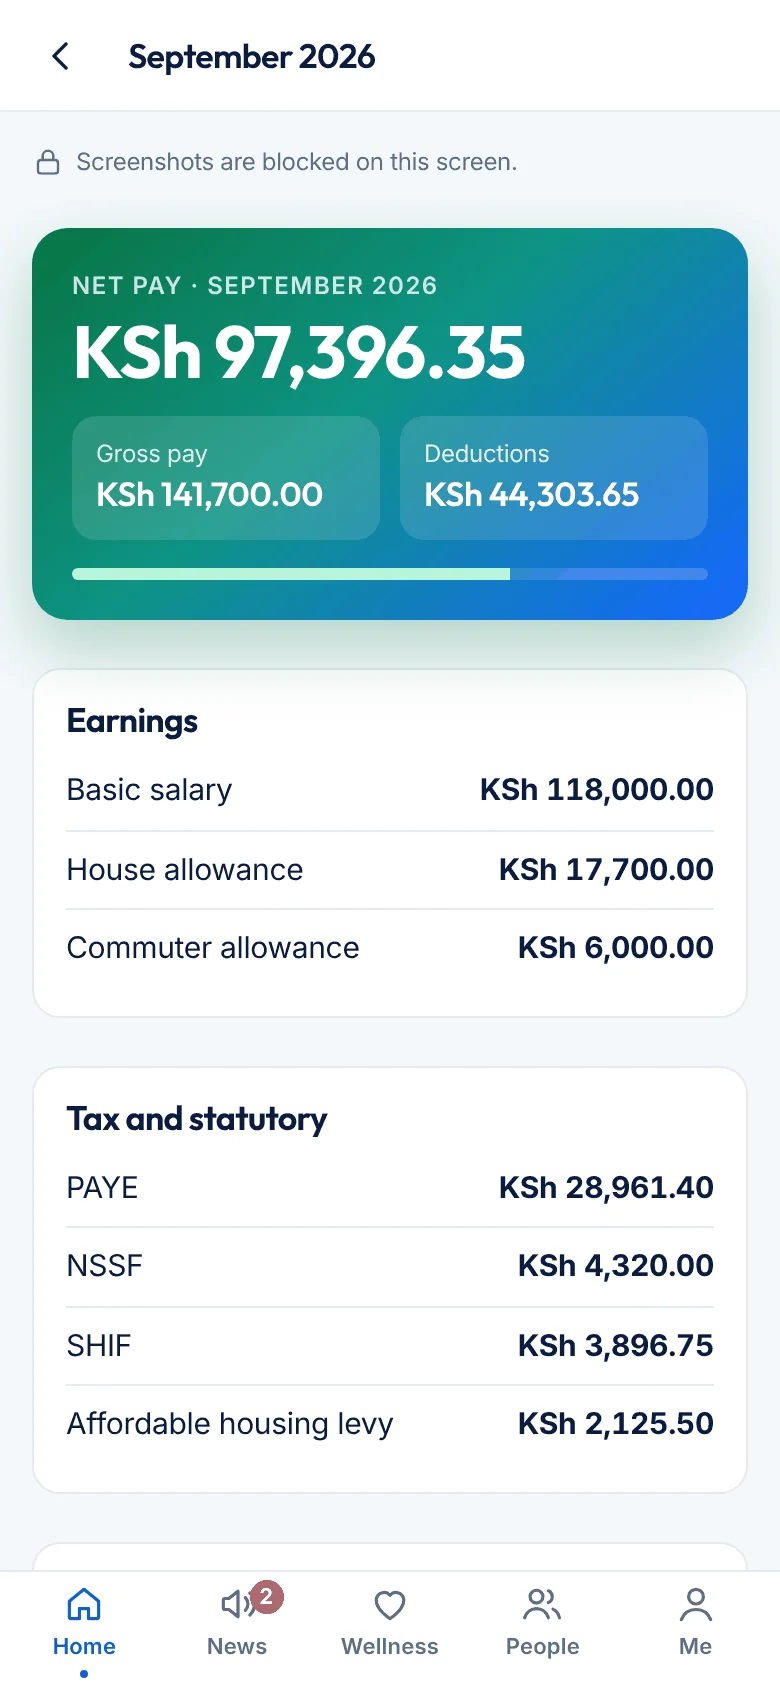
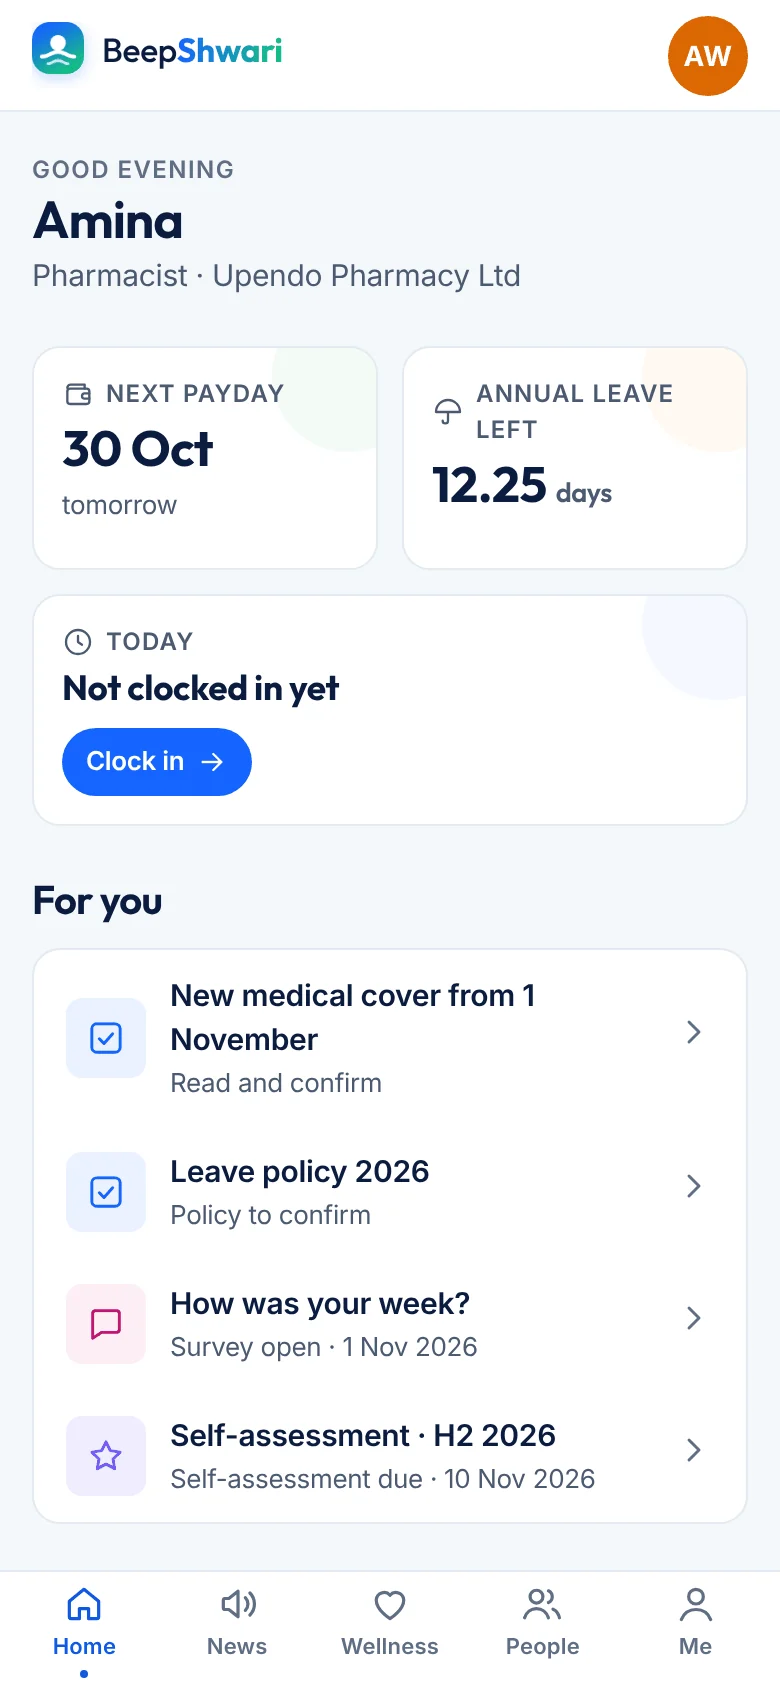
See HR & Payroll →BeepShwariPayslips on every phoneYour staff get their payslips and P9s behind a PIN, apply for leave, clock in and read company news, in one app.
Meet BeepShwari →

How it works
The calculator follows the same order a Kenyan payroll does. Here it is for 2026.
Basic salary plus cash allowances. Non-cash benefits count for tax once they pass the monthly threshold.
NSSF is 6% in two tiers up to the upper limit. SHIF is 2.75% of gross (minimum KSh 300). The housing levy is 1.5% of gross.
NSSF and pension (up to KSh 30,000 a month), SHIF, housing levy, post-retirement medical fund and mortgage interest all reduce taxable pay.
10% on the first KSh 24,000, 25% to KSh 32,333, 30% to KSh 500,000, 32.5% to KSh 800,000 and 35% above.
Personal relief of KSh 2,400 a month, plus 15% of qualifying insurance premiums. PAYE can’t go below zero.
Gross pay minus NSSF, SHIF, housing levy, PAYE and any pension you pay through payroll. Your employer pays matching NSSF, 1.5% housing levy and KSh 50 NITA on top.
Rate history
Every PAYE, NSSF, NHIF, SHIF and housing levy change the calculator knows about. Pick any of these months above to see its effect on pay.
| Effective | What changed |
|---|---|
| In force, Jan 2023 | Monthly PAYE bands: 10% to KSh 24,000, 25% to KSh 32,333 and 30% above. |
| In force, Jan 2023 | Personal relief KSh 2,400 a month. |
| In force, Jan 2023 | Insurance relief: 15% of premiums and NHIF, up to KSh 5,000 a month. |
| In force, Jan 2023 | NHIF by salary band, from KSh 150 to KSh 1,700 a month (employee only). |
| In force, Jan 2023 | Old NSSF: KSh 200 employee + KSh 200 employer. |
| In force, Jan 2023 | Only NSSF and pension contributions reduce taxable pay (combined cap KSh 20,000 a month). |
| In force, Jan 2023 | NITA training levy KSh 50 per employee a month, paid by the employer. |
| In force, Jan 2023 | Mortgage interest deduction up to KSh 25,000 a month. |
| In force, Jan 2023 | Registered persons with disability: first KSh 150,000 a month is tax-free. |
| In force, Jan 2023 | Tax-free per diem KSh 2,000 a day. |
| In force, Jan 2023 | Tax-free meal benefit KSh 4,000 a month. |
| In force, Jan 2023 | Non-cash benefits tax-free up to KSh 3,000 a month. |
| 1 Feb 2023 | NSSF Year 1: upper limit is KSh 18,000 (lower limit KSh 6,000), 6% each from employee and employer, up to KSh 1,080 each. |
| 1 Jul 2023 | Finance Act 2023 PAYE bands: 10% to KSh 24,000, 25% to KSh 32,333, 30% to KSh 500,000, 32.5% to KSh 800,000 and 35% above. |
| 1 Jul 2023 | Housing levy starts: 1.5% employee + 1.5% employer of gross pay. |
| 1 Feb 2024 | Housing levy suspended after the Court of Appeal ruling: none deducted. |
| 1 Feb 2024 | NSSF Year 2: upper limit rises to KSh 36,000 (lower limit KSh 7,000), 6% each from employee and employer, up to KSh 2,160 each. |
| 19 Mar 2024 (March payroll) | Affordable housing relief: 15% of your housing levy, up to KSh 9,000 a month. |
| 19 Mar 2024 (March payroll) | Affordable Housing Act 2024: housing levy restarts at 1.5% employee + 1.5% employer of gross pay. |
| 1 Oct 2024 | Insurance relief no longer covers health contributions: SHIF does not qualify (KRA notice, 8 Nov 2024). |
| 1 Oct 2024 | SHIF replaces NHIF: 2.75% of gross pay, minimum KSh 300, no upper limit (employee only). |
| 27 Dec 2024 (December payroll) | Tax Laws (Amendment) Act 2024: SHIF, housing levy and post-retirement medical fund contributions become tax-deductible; housing levy relief ends; pension + NSSF cap rises to KSh 30,000 a month. |
| 27 Dec 2024 (December payroll) | Mortgage interest deduction cap rises to KSh 30,000 a month. |
| 27 Dec 2024 (December payroll) | Post-retirement medical fund contributions deductible up to KSh 15,000 a month. |
| 27 Dec 2024 (December payroll) | Tax-free meal benefit rises to KSh 5,000 a month. |
| 27 Dec 2024 (December payroll) | Non-cash benefit threshold rises to KSh 5,000 a month. |
| 1 Feb 2025 | NSSF Year 3: upper limit rises to KSh 72,000 (lower limit KSh 8,000), 6% each from employee and employer, up to KSh 4,320 each. |
| 1 Jul 2025 | Tax-free per diem rises to KSh 10,000 a day. |
| 1 Feb 2026 | NSSF Year 4: upper limit rises to KSh 108,000 (lower limit KSh 9,000), 6% each from employee and employer, up to KSh 6,480 each. |
FAQ
Online now · 24/7Our Nairobi team answers calls, WhatsApp and email day and night.
Call us+254 725 333 888WhatsAppChat with our teamContactSend us a messageNHIF was a flat amount by salary band, from KSh 150 to KSh 1,700 a month. It ended on 30 September 2024. SHIF replaced it from the October 2024 payroll at 2.75% of gross pay, with a minimum of KSh 300 and no upper limit. Only the employee pays it. NHIF earned 15% insurance relief. SHIF doesn’t, but since December 2024 it reduces taxable pay instead.
1.5% of gross pay from the employee and another 1.5% from the employer, with no cap. It started in July 2023, was suspended for February 2024 and restarted under the Affordable Housing Act 2024 with the March 2024 payroll. Employers remit it to KRA by the 9th working day after the month ends.
From February 2026 (Year 4 of the NSSF Act 2013), employee and employer each pay 6% of pensionable pay. Tier I covers pay up to KSh 9,000 (KSh 540), and Tier II covers pay from KSh 9,000 to KSh 108,000 (up to KSh 5,940). The most each side pays is KSh 6,480 a month. The limits were KSh 6,000/18,000 in 2023, 7,000/36,000 in 2024 and 8,000/72,000 in 2025.
Yes, since the Tax Laws (Amendment) Act 2024, which took effect on 27 December 2024 and was applied from the December 2024 payroll. SHIF, the housing levy and post-retirement medical fund contributions now reduce taxable pay. Before that, the housing levy earned 15% relief (March to November 2024), and SHIF got neither a deduction nor relief in October and November 2024.
KSh 2,400 a month (KSh 28,800 a year) for every resident employee. It comes off the tax worked out on the PAYE bands. If your tax is less than your reliefs, PAYE is zero; unused relief isn’t paid back.
PAYE (with the P10 return on iTax), SHIF, NSSF and the NITA levy are due by the 9th of the following month. KRA’s notice gives the housing levy until the 9th working day after month end, but most employers pay it by the 9th with everything else.
This calculator gives estimates for guidance only. It is not tax, legal or payroll advice. It assumes a resident employee paid monthly and uses the Kenyan statutory rules we have on record as of 29 October 2026. Court rulings, KRA notices and your employer’s own practice can change the result. Confirm figures with the Kenya Revenue Authority or a qualified tax adviser before you rely on them.
Our figures are cross-checked across several professional summaries of the Acts and KRA notices. Where the law or court rulings left room for doubt, we follow what most Kenyan payroll systems do, and the notes under your result say so.